Qualcomm is a cautious “show me” story
Qualcomm (QCOM) $200 has moved up 19% in the past year, but was an underperformer in the last 5, with just a 50% increase. The loss of the iPhone business led to peak revenue of $44Bn in FY2024, which declined to $35Bn before rebounding to the same level in FY 2026. The auto segment led the charge growing to over $7Bn a year.
There are a lot of opportunities and to QCOM’s credit it has been seriously pursuing data center ASICs and connectivity revenues. I would think it is a cautious buy on declines for small quantities for now and then evaluate its progress.
Positives
- Momentum in data center contracts - QCOM is aiming for $15Bn in contracts by 2029 and has made some progress in 2026.
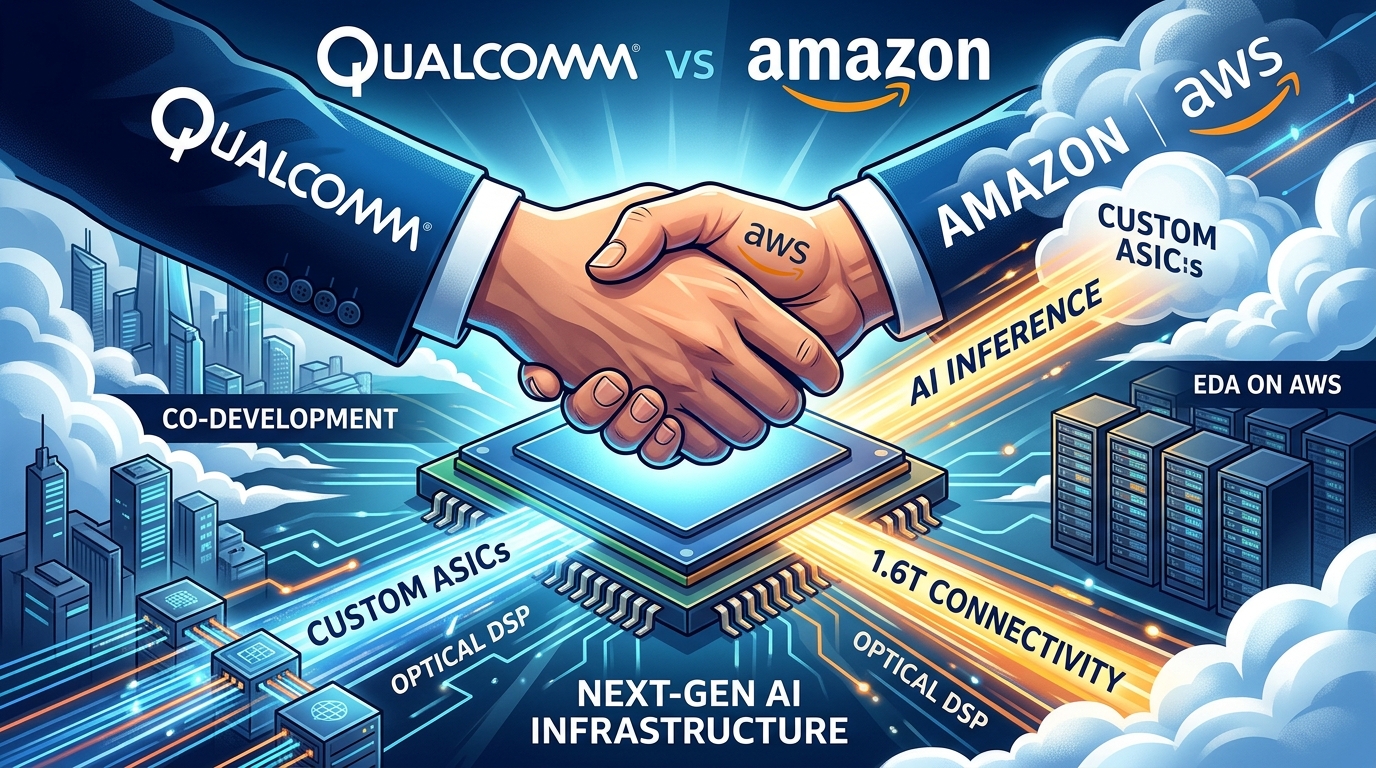
- Amazon has confirmed a multi generation contract with Qualcomm for ASICs and fiber optic connectivity chips.
- There are also reports of a possible contract with a large unnamed hyperscaler, likely to be Bytedance.
- Good growth in connectivity - DSPs, optics also fueled by acquisitions amid a massive shortage of demand. This is also like to remain in the higher end 1.6 Terabits, this is the right segment as connectivity remains crucial.
- Auto is the jewel in the crown with 61% growth - Qualcomm is a market leader by far, it beat its own forecasts of $6Bn to get to an ARR of $7Bn - this is very impressive, leading Nvidia by a wide margin in auto revenues.
- Their licensing and royalty revenue segment has a treasure trove of patents and is is high margin recurring business.
Negatives
- The loss of Apple’s business , which took five years of a slow decline has reduced the mobile phone business, which is still its biggest segment. I guess what troubles investors is that this was known for several years, and QCOM couldn’t get other growth products to make up for the loss of this revenue. Thus there is a great deal of skepticism about QCOM’s prospects - filling that large a gap is difficult. Semiconductors need constant innovation and sometimes the mobile phone leader struggles to get a foothold in other segments like data centers. Systems on chips are decades long efforts and switching costs are enormous for customers. What is a huge moat for Qualcomm in autos becomes a huge barrier to entry in data centers.
- Furthermore, their biggest customer in mobile is Samsung, and Samsung is a semiconductor powerhouse by itself - there is no guarantee that it would keep using QCOM for Galaxy and other handsets.
- QCOM’s Snapdragon chips and chip architecture doesn’t have the strength of Nvidia and AMD. It constantly falls short but is getting traction in ASICs, (Application Specific semis) for limited ranges of workloads - that is a good place to be and will continue to grow as fast if not faster than general purpose computing.
- The deal with Microsoft’s Surface to deliver AI computing at the edge in personal computers is not quite the big bang it was supposed to be - it disappointed investors, but it remains an ongoing relationship.
The bottom line - A cautious buy on declines
The $15Bn data center promise will be closely scrutinized, and QCOM has to show progress; this growth is also going to be acquisition led, so we’ll have to look at spending as well.
The valuation is reasonable at 19x 2027 earnings but growth only starts in FY2028 from where it should grow 15-17% annually. Similarly for sales - growth starts from FY2027-2028 and can grow 10-12% year - investors haven’t driven up the valuation as much and it is about 5x sales.