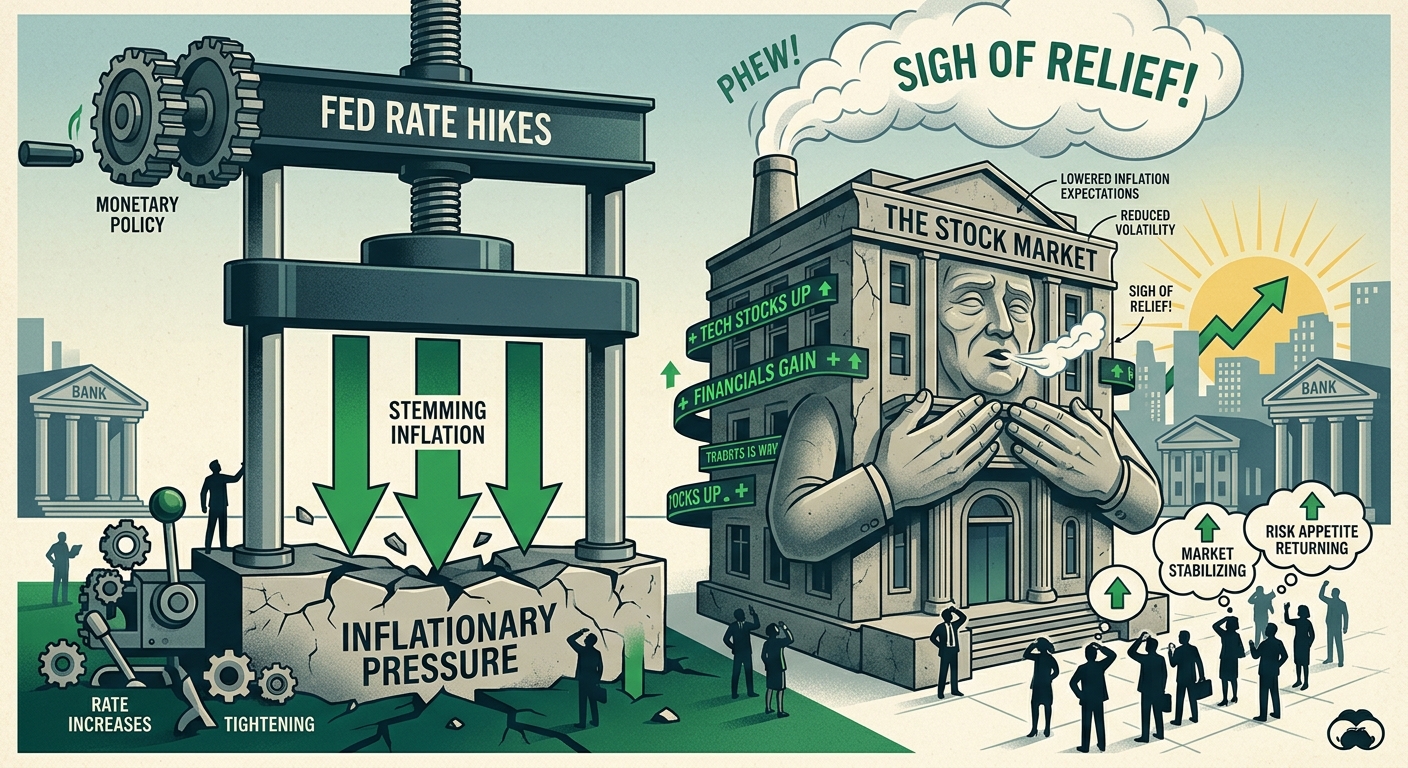
I believe that the Fed’s decision to step in with a 25-basis-point hike was a right decision and it has brought some stability to the bond market. Micron’s earnings on Sep 30th is now the biggest catalyst and in the run-up should provide support to semis and data center stocks - a rising tide lifting many boats. “Buy The Dip” has come back strongly
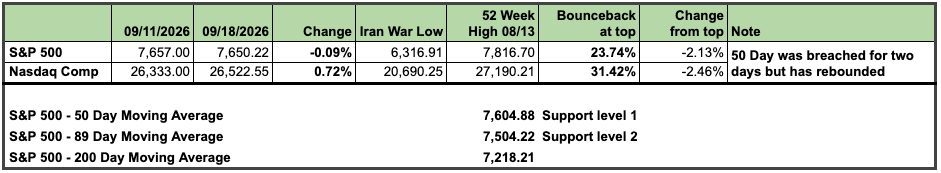
Both the S&P 500 and the Nasdaq Composite rebounded from their lows of Wednesday Sep 16th, after the FOMC raised the Fed Funds rate by 0.25% to 3.75% to 4%. The rate hike was widely expected, and not hiking would have sunk the market. The hike was bullish as I had posited in the previous newsletter, mostly reaffirming the Federal Reserve’s capabilities of fighting inflation and staying independent of the Trump administration.
The first three days of the week were bad with a 1.5% drop, as markets worried whether the Feds would completely reduce their credibility as political stooges. There was considerable agreement that inflation needed to be controlled and even the CPI from Sep 11th had indicated stubborn inflation, way above the Fed’s target of 2%. A BOFA fund manager’s survey strongly conveyed that the Feds would be remiss not to hike, and the markets heaved a collective sigh of relief when the Feds eventually did.
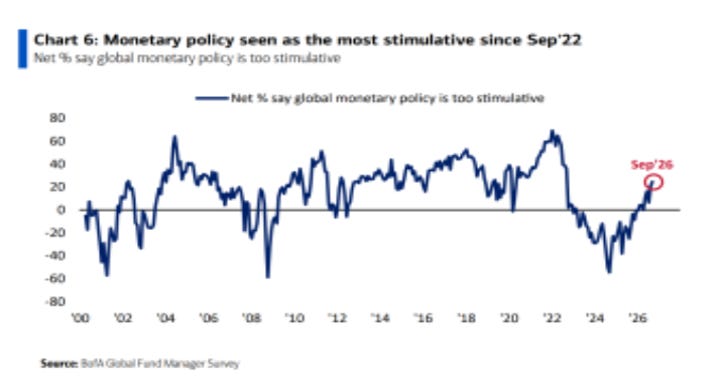
The BofA fund manager survey, which came out a couple of days before the FOMC meeting had three important findings that proved very influential regarding the rate hike.
1. 25% of of fund managers believed that monetary conditions were way too easy
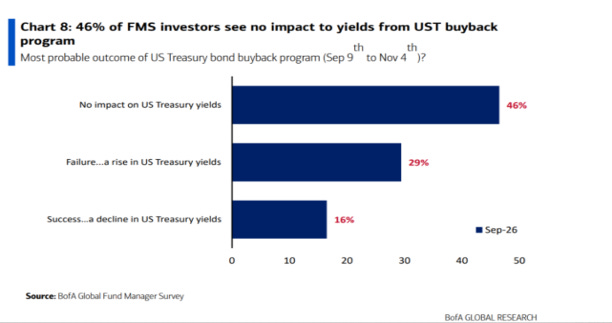
2. 46% of fund managers saw no help from the Treasury’s bond buyback program. 29% feel that it would lead to a rise in yields instead of a drop. Just the opposite of what a buyback is supposed to accompolish.
3. 33% of respondents felt that a “disorderly” rise in bond yields was the biggest tail risk. This is higher than the 28% citing AI! The third highest tail risk at 24% was a second bout of inflation. Clearly the treasury and the Fed have their work cut out for them. No surprise that few people are buying bonds even with the 10 year above 5% and the 30-year above 5.38%.
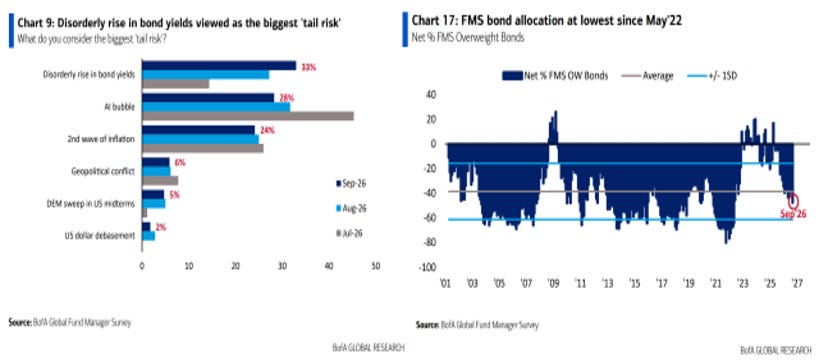
Fund managers didn’t want to lose faith in the Federal Reserve’s capacity to keep the economy humming with sound interest rate policies; Cutting interest rates with stubborn inflation and high-budget deficits would have created a bubble. Funding buybacks without a resulting drop in yields made little sense, it eventually would have led to a disorderly rise in gilts with investors losing faith in treasuries. I believe that the Fed’s decision to step in with a 25-basis-point hike was a right decision and it has brought some stability to the bond market.
The correction for higher interest rates, inflation worries, and fears of an AI bubble maxed out at 4% to 7,508. I believe that, at least for now, “Buy The Dip” has come back strongly and in the absence of macro-economic bearish factors the markets should stay steady if not strong. Micron’s earnings on Sep 30th is now the biggest catalyst and in the run-up should provide support to semis and data center stocks - a rising tide lifting many boats.
I bought these stocks on Thursday, 09/17/2026