Vertiv (VRT)'s core competency is end-to-end system deployment for data centers for electrification and thermal management. Vertiv's Data Center Focus Is A Huge Competitive Advantage: Buy The Stock
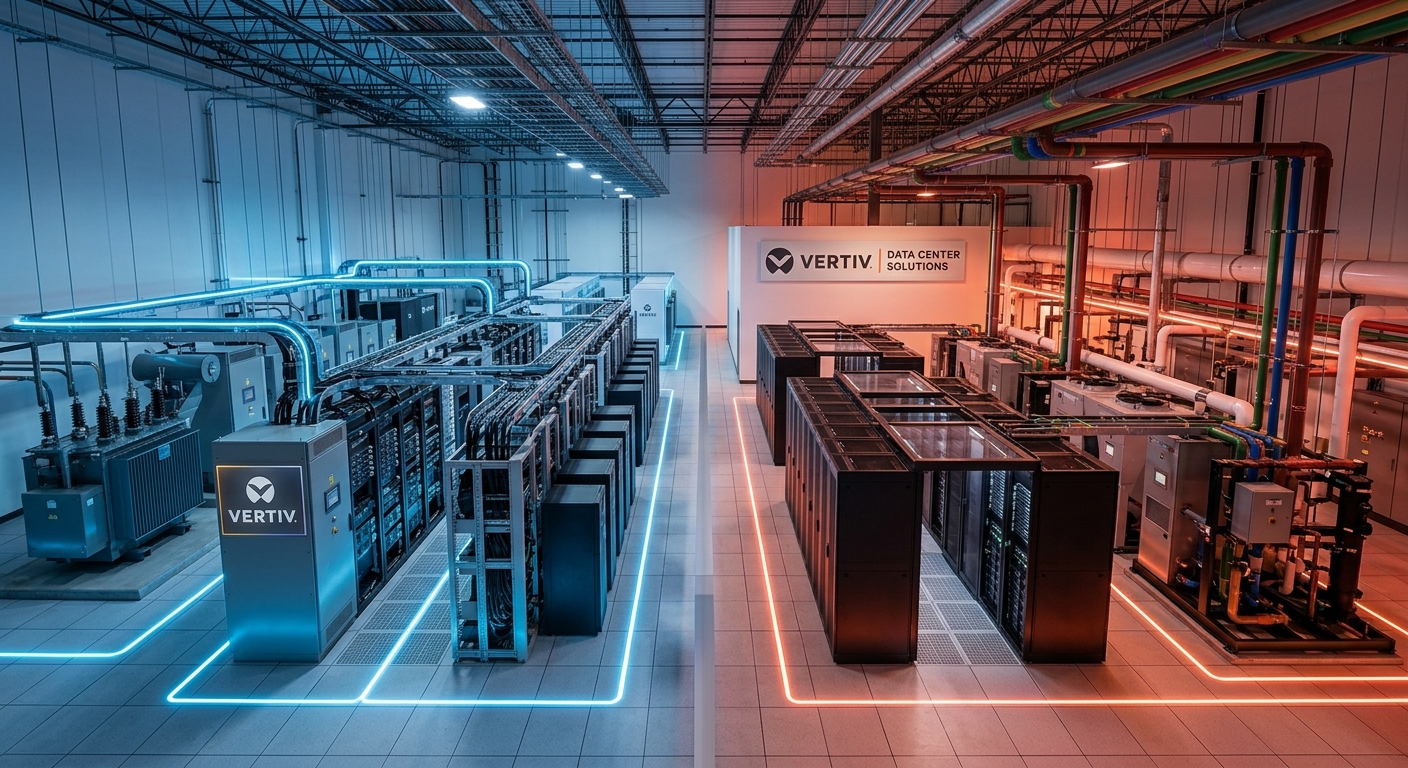
The speed, size, and scale of new data center deployments require significant project engineering and management capabilities and collaboration and partnerships at scale - this is not about equipment. Data centers are coming up at fairly ridiculous speeds and facing hurdles of electrification, thermal, and water management. In this environment, which needs constant innovation and firefighting, the $14Bn Vertiv, with 85% of revenue from data centers, has the advantage of scale, which creates a significant barrier to entry from newer entrants, plus a lot of switching costs for their customers. There is very little room for plain vanilla solutions because multiple power architectures have become the norm, and the vendor has to support all of them. Orchestration and project management are key prerequisites, and Vertiv has plenty of experience and competency in providing those.
The valuation is reasonable given its growth with the P/E dropping to 21 two years out, with the PEG compellingly low at just 0.6. There is operating leverage, with 19% revenue growth providing 24% earnings growth.
Buy the stock for these reasons:
Here is the entire article at Seeking Alpha.