I will buy the Anthropic (ANT), based on Professor Damodaran's article because of his forecast of $1 Tr in 2036 revenues. His base case considers that there will be verticals like drug discovery, and the spoils of these discoveries will accrue to Anthropic itself through their medical arm. I also believe that ANT has strong operating leverage.
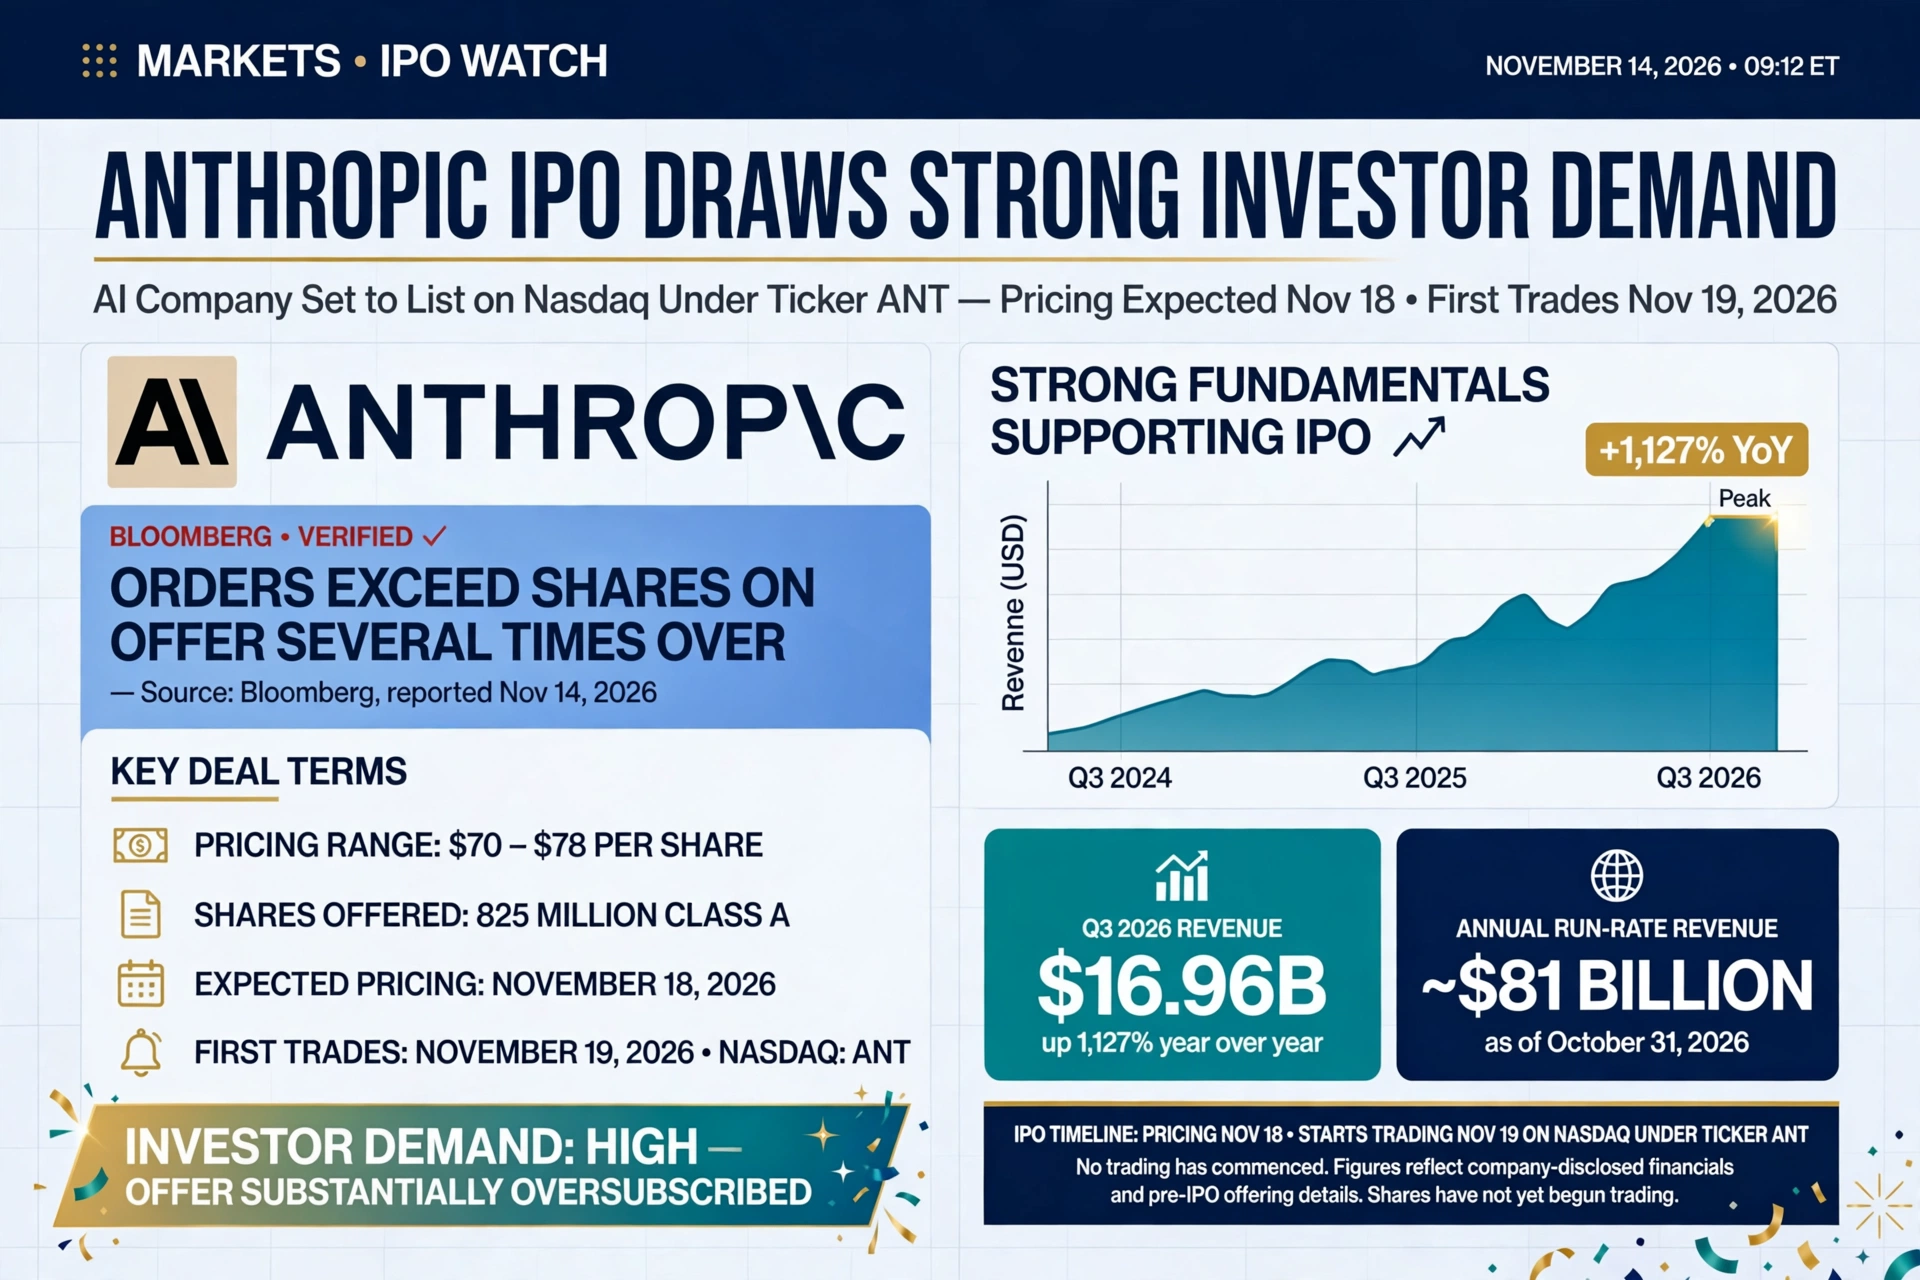
I was very impressed with the professor's work and more importantly it was reassuring that the professor had forecasted close to $1 trillion in 2036 revenues for Anthropic (ANT). Knowing the professor’s history this is a remarkable forecast. He is usually a lot more conservative and has foregone opportunities when the uncertainty was high and given how uncertain the growth of this whole AI ecosystem is, his estimate was about 30% higher than mine! His base case takes into account that there will be verticals like drug discovery, and the spoils of these discoveries will accrue to Anthropic itself through their medical arm, which seem to make the bass case possible.
The assumptions that he has made towards his forecasts are also fairly sound. The higher margin business is actually happening right now because the revenues are based on usage and the revenues are sticky because of the wide customer base with about 1,100 customers spending more than $1 million each year. Anthropic's Q2-2026 operating margin strength of 10% confirmed that operating leverage is already in affect. The compute costs are also not rising as high as revenues, which, of course, is essential for any operating leverage and for the success of any business. There is an element of shifting a large amount of variable cost to a fixed component.
What does that mean? The most expensive component of compute is the GPU, which means that if you deploy an X number of GPUs, the depreciation on those GPUs will be on a five to six year basis and it’s not like the variable component will fluctuate heavily each time an inference is run. Yes, there will be the cost of utilities among other smaller costs but the base cost, which is the GPU itself is an investment with a depreciation that is fixed and because of the larger revenue, this becomes more of a fixed component than a variable component. Think of it a little bit like Netflix - Netflix buys a title from the studio for several years, and amortizes its cost. each time we watch a movie, the cost of running it is tiny - the variable component is low.
And the prof has done an excellent job of explaining how this model could actually be profitable - Anthropic, OpenAI, Meta and others will only get better at it.
I also like that he has shown the revenues from the five big distributors that are contributing more than 25% of Anthropic’s revenues. That is normal. Anthropic will get a lot of business from AWS because AWS is going to tack it onto their clients and are happy to part with 15 to 20% to Anthropic. That’s just how the business model is going to work and I don’t see that as a big concentration risk - large distributors such as AWS and Azure are a very, very essential part of this business.
Let’s talk about some of the weaknesses and the potential bear case. The prof has taken a compounded annual growth rate of 26% through 2036, but to me the biggest risk is the volatility over the next 2 to 3 years - I don’t see investors having that kind of patience. Ironically, some of that volatility will not be because of overbuilding, it’ll be because of the lack of compute available to Anthropic even as it has orders so it’s actually going to be both ways. Anthropic doesn’t mind if you go out and build five times the data centers that are available today. That means it will be just cheaper for it to get the over supply, though not for the rest of the industry.
I have a hard time trying to do a smooth forecast through 2036 and with a conservative approach I get to about $600Bn by 2036 but it could be very bumpy to be sure. Anthropic too warned of slowing growth for three reasons, - not enough compute, competition and it is impossible to keep up with that’s just the law of large numbers.
What I found reassuring was that Prof Ashwath emphasized the sovereignty of data which even Alex Karp (Palantir) quite strongly defended as an enterprise’s most important asset. The proprietary data of its customers, yield the best margins and pricing for Anthropic, which means two things - that Anthropic’s or other foundational model’s commodity businesses are not going to destroy the SaaS companies, b) selective targeting of businesses or building vertical centric models is the much better way to go than one shoe fitting all. Which is really a win-win for everybody.
I think the professor also makes a good case that the initial progress will be made at improving efficiencies and not really get to the level of displacing employees for about half a decade at least. I would prefer to see more visibility in another 3 to 4 years if that changes, honestly, it’s impossible to predict that part right now. The growth in GP and the steadiness in employment suggest that job losses are not severe and we are not looking into an abyss.
Professor Damodaran had also refuted Citrini’s doomsday scenario, and this article on Anthropic showing solid revenue growth is very reassuring especially when the whole AI build out is being questioned.