You've reached your free article limit! Create an account or upgrade for unlimited access.

See Plans

You've reached your 20 article limit. Upgrade for unlimited access.

See Plans

Shark Ninja's (SN) Brilliant Strategy And Execution Makes The Stock A Compelling Buy

Shark Ninja's market leadership, brand recognition, loyalty and younger customer base deserves a premium. Its growth strategy of category expansion, innovation, and international growth is huge. I expect 12-15% returns annually for the next 5 years or so. This is a long-term buy and hold for me.
By 

Fountainhead Investing

Published 

September 16, 2026

Shark Ninja (SN) $174 - deserves a premium

I am going to accumulate steadily, especially on declines. The stock has appreciated 50% in the past year but it remains a strong long term play.

Barron’s is carrying a story on it today, and I need to increase my non-tech exposure, with other high quality business model companies. While Shark Ninja has become expensive at over 20x earnings it has legs and could be a consistent presence in homes for several decades, with a loyal and younger customer base. I think its market leadership, brand recognition, loyalty and younger customer base deserves a premium. Earnings will grow into the price and bring down the premium over time. The 25 P/E for 2026 earnings drops to 21 next year with earnings growth of 16% resulting in a fairly manageable PEG ratio of 1.25

Industry/Sector/Type - Appliances but with strong brand marketing and recognition makes it a secular growth category.

Biggest catalysts for the stock - The constant new product lineup, brand recognition and “accessorizing” of appliances boosted with its social media presence will remain catalysts for years to come.
Positives

  1. A fresh and innovative look at a musty, cyclical, slow moving home appliance category, where Shark Ninja has succeeded by making inroads into younger cohorts and shaking up buying habits.
  2. One of the biggest drawbacks of the appliance industry was the replacement cycle, and Shark Ninja seems to have shortened it considerably by continuous product upgrades.
  3. Moreover, it keeps expanding into adjacent and newer categories, fully exploiting its brand. This is very clever marketing and Shark Ninja products include coffee makers, air purifiers, vacuums, air fryers, hair products and beverage systems.
  4. A clear cut strategy of affordable pricing with better/newer features with a strong emphasis on technology and upgrades.5.
  5. Their branding has succeeded in “accessorizing” some of their products - Form over Function, but also delivering on performance, so it’s not a gimmick.
  6. Their social media presence, (especially on TikTok) is a huge competitive advantage - it also helps higher margin direct to consumer sales.
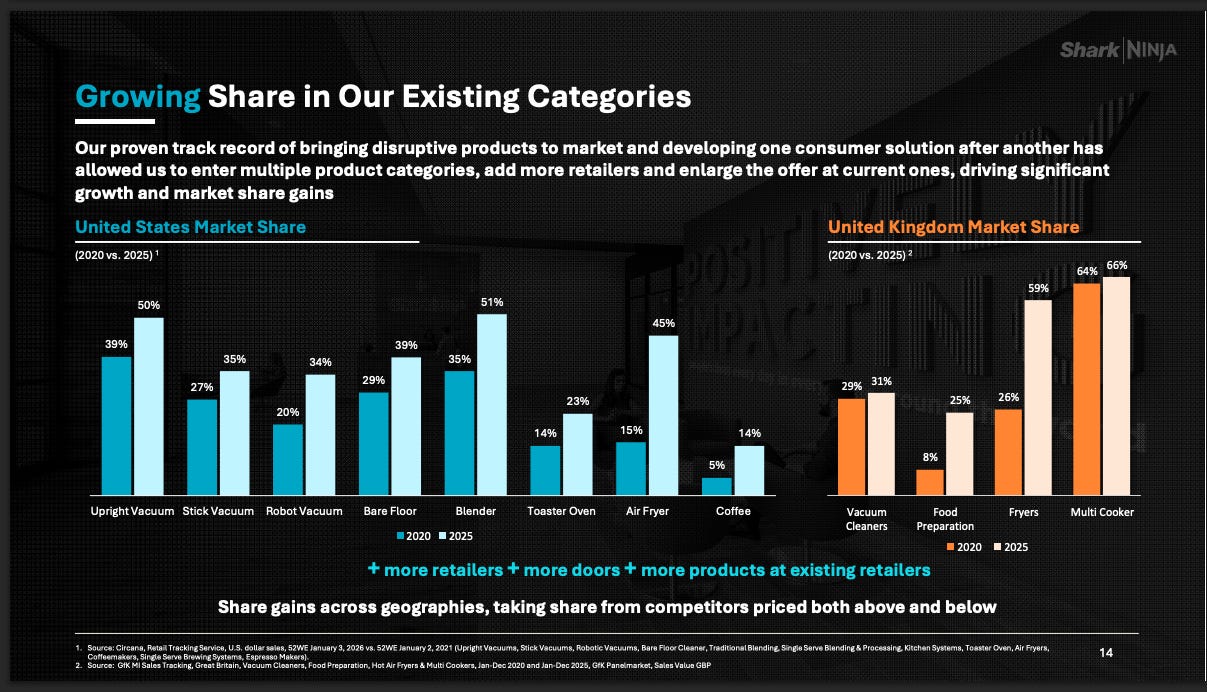
  7. Consistent market share increases in all its categories, and the good thing this is a very dynamic group - they go for very diverse and new markets - it has a strong engineering pool to do so.

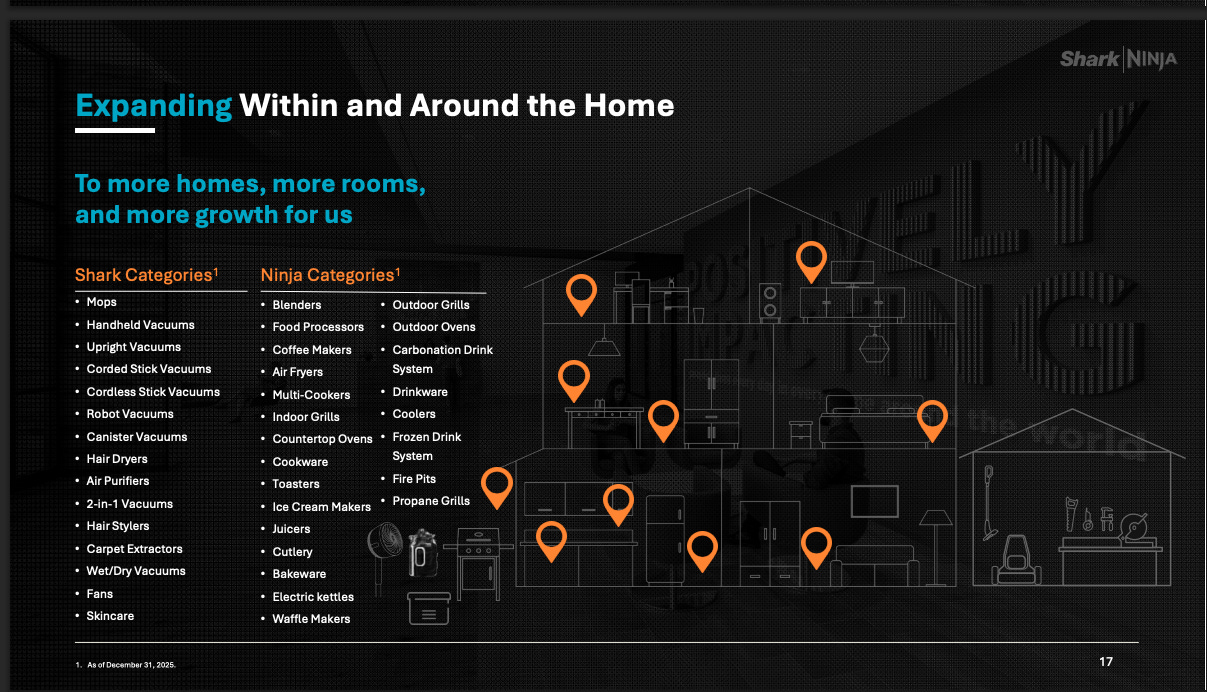
The Home Occupation by Shark Ninja leave no room unturned

Growing Market Share in each category

Negatives

  1. Consistently fighting entrenched incumbents - because of the wide number of markets and categories it has to fend off competition in all of them, and we’re talking about household names like Dyson, Britta, Bissell, Cuisinart, and Weber to name a few.
  2. Add to that international expansion where it has to fight giants like Nestle (Nespresso), Siemens, and Phillips across categories.
  3. Replacement cycles of 5-7 years may not shorten even with constant upgrades, Yes, Shark Ninja does go for an 18 month upgrade cycle but it is tough to accomplish - much of Shark Ninja’s growth has come from category expansion, and not necessarily faster replacement.
  4. All categories are not growing as fast - the Food preparation category grew only 3% last quarter, and its largest segment cleaning grew 17%. We will see points of saturation and some failures.

Return

1 Year - 54%

5 Year - The stock IPO’d at $32 less than 5 years ago but that’s a 5x performance, very commendable.

The stock is currently 12% below its 52-week high of $192

Valuation

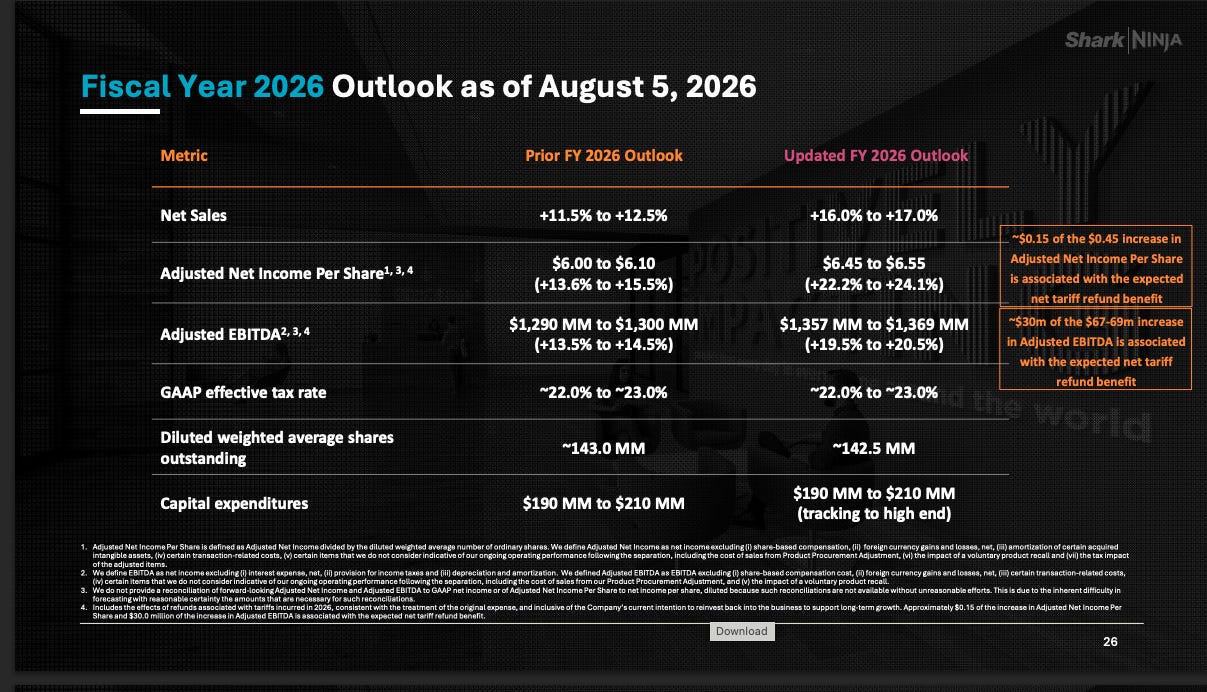
The valuation is a little on the higher side, but not to apoint where I wouldn’t buy the stock, and as we can see below, they did upgrade a fairly conservative estimate in 2026, so these forecasts could be conservative.

P/S Ratio 3.4 Sales Growth 11 to 13% P/S Growth Ratio 0.25

P/E 21 Earnings Growth 14-15% PEG 1.5

Cash Flow Margin - 11%

Operating Margin - 15%

As we can see below, conservative estimates were raised in 2026, so Seeking Alpha analysts might be too conservative.
Price Target : Given SN’s growth strategy of category expansion, innovation, and international growth I expect 12-15% returns annually for the next 5 years or so. This is a long-term buy and hold for me.