TJX's low price, and its dividend yield of 1.5% are appealing, but the stock’s 5 year performance is only 80%, so one has to be very careful about the entry price. I would either wait for a signal on MarMaxx improvements or even a further decline to buy.
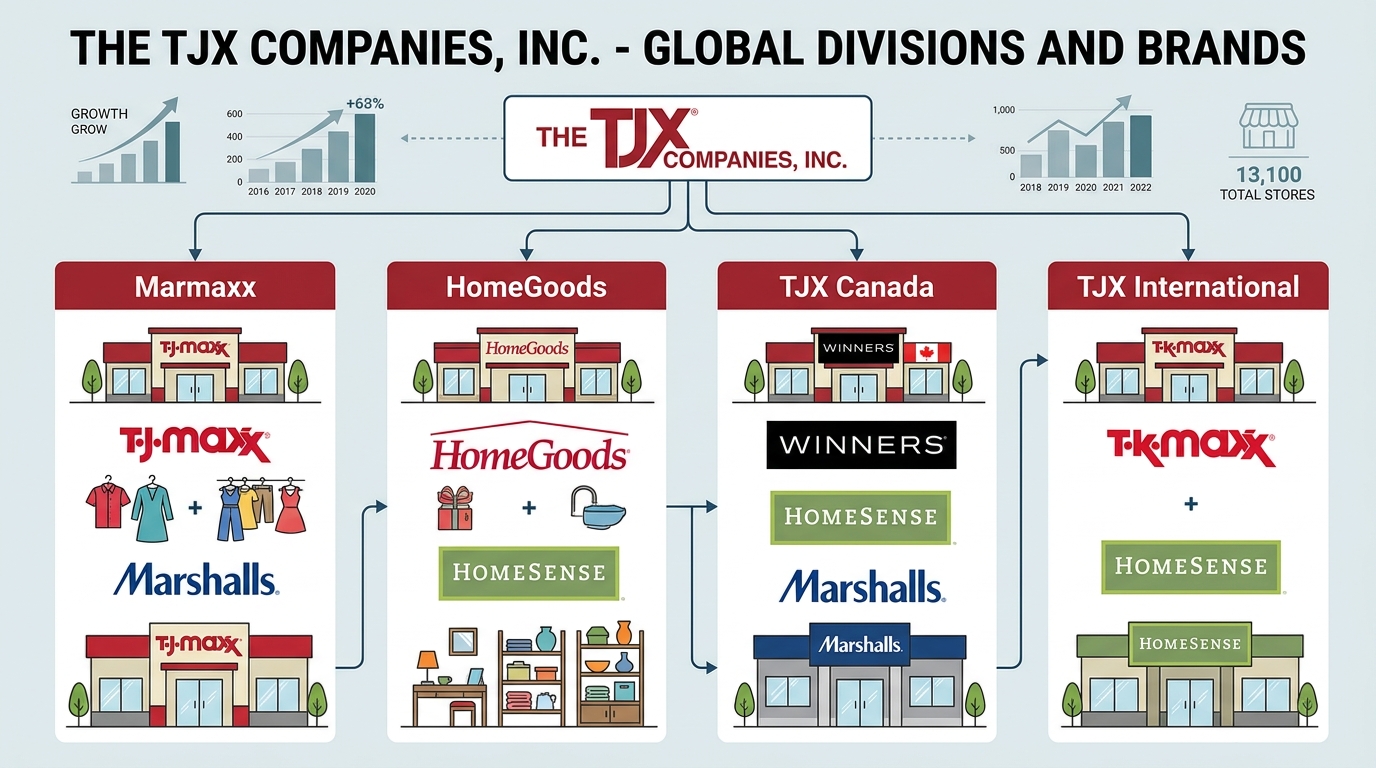
TJ Companies (TJX) $125, the discount retailer owns TJ Maxx, Home Goods and Marshalls. It’s stock price has become reasonable after a 20% drop from its 52-week high of $170, but unless the company demonstrates improvement in its largest segment - MarMaxx, it would be prudent to wait.
Its MarMaxx (U.S.) segment, had a poor showing with sales increasing just 3% from $8.84B to $9.10B, and comps faring even worse - just 1%, dropping from a 3% increase the prior-year quarter. With MarMaxx contributing 60% of sales, any further weakness will drag the stock down - it would mean more than poor merchandising and cast doubts on management’s execution.Unfortunately, this is also a volume problem as the number of customer transactions declined, which could indicate that customers didn’t find alternate items easily.
Management attributed this to poor merchandising. CEO Ernie Herrman -
We could have executed our store mix better, and by that I mean we could have been sharper on having the right goods in the right stores at the right time.
Management has started working on merchandising and have indicated seeing early improvements.
Hold: It is a 12% earnings grower priced at 24 - that seems a little unusual for a retailer, especially a discount retailer, though TJX has been very successful as a cookie cutter in a difficult environment. I think the premium is deserved because of the oligopoly, market leadership and consistency.
The low price, 20% below its 52-week high, and the dividend yield of 1.5% are appealing, but the stock’s 5 year performance is only 80%, so one has to be very careful about the entry price.
I would either wait for a signal on MarMaxx improvements or even a further decline to buy.