Personal income numbers were not as positive as income came in lower than consensus but expenses beat estimates. Core PCE inflation rises less than expected in September - a good sign.
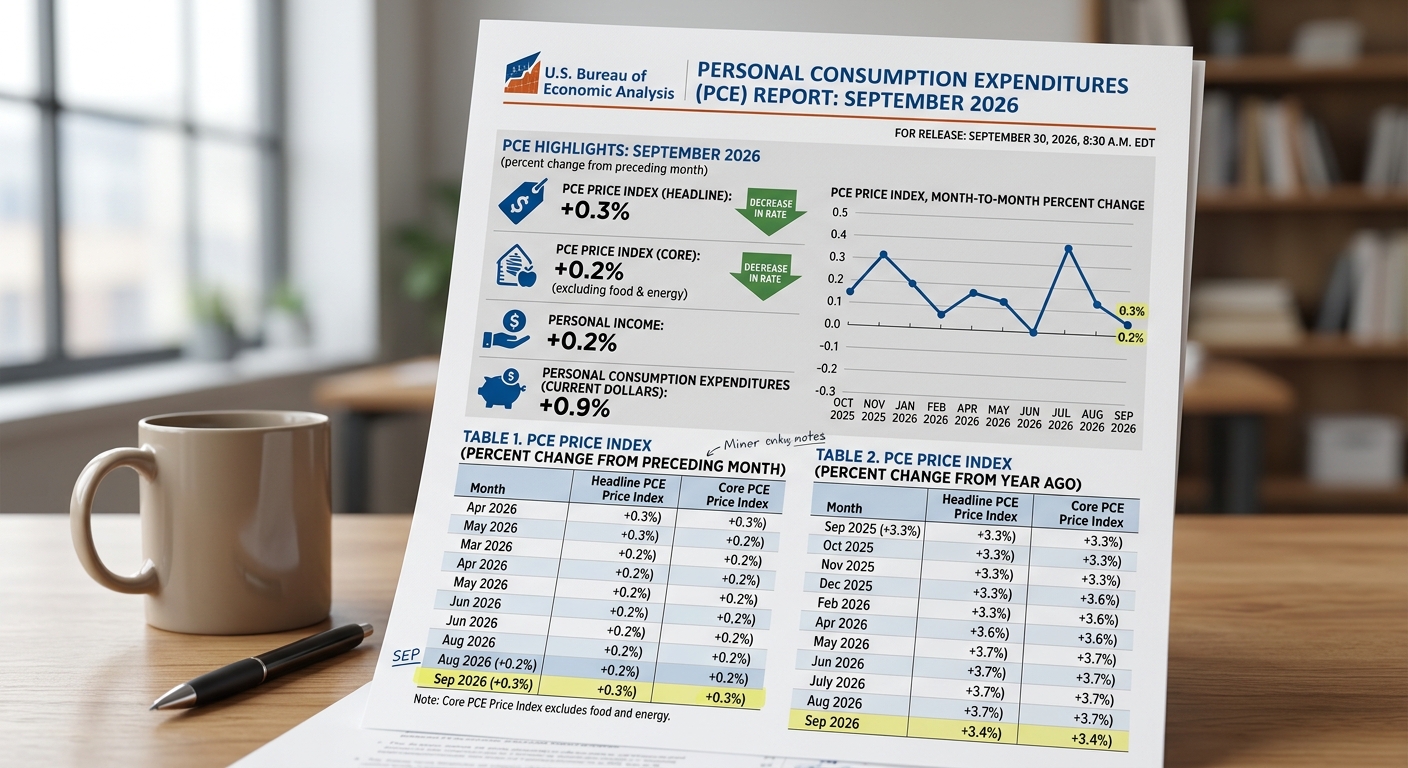
This should help Federal Reserve doves with inflation coming in a little more benign than expectations.
Core PCE Price Index:
Monthly: +0.2% M/M vs. +0.3% consensus and +0.1% prior (revised from +0.2%). Good to see this receding, the core index strips out volatile components.
Annual: +3.0% Y/Y vs. +3.3% consensus and +3.0% prior (revised from +3.3%). Still far from the Fed's objectives of 2% but we'll take any positive news.
PCE Price Index:
Monthly: +0.3% M/M vs. +0.4% consensus and +0.1% prior (revised from +0.2%). This is a big positive because it includes oil prices.
Annual: +3.4% Y/Y vs. +3.7% consensus and +3.4% prior (revised from +3.7%). The headline needs to come down below 3% per year/
Personal Income and Expenses:
Personal income numbers were not as positive as income came in lower than consensus but expenses beat estimates. It would be interesting to see how this is intepreted by the Fed board - incomes not rising enough should prompt a dovish response.
Personal Income: +0.2% vs. +0.5% consensus and +0.3% prior (revised from +0.4%). The miss is quite a bit and even the prior month was revised lower.
Personal Consumption Expenditures: +0.9% vs. +0.8% consensus and +0.1% prior (revised from 0.2%).