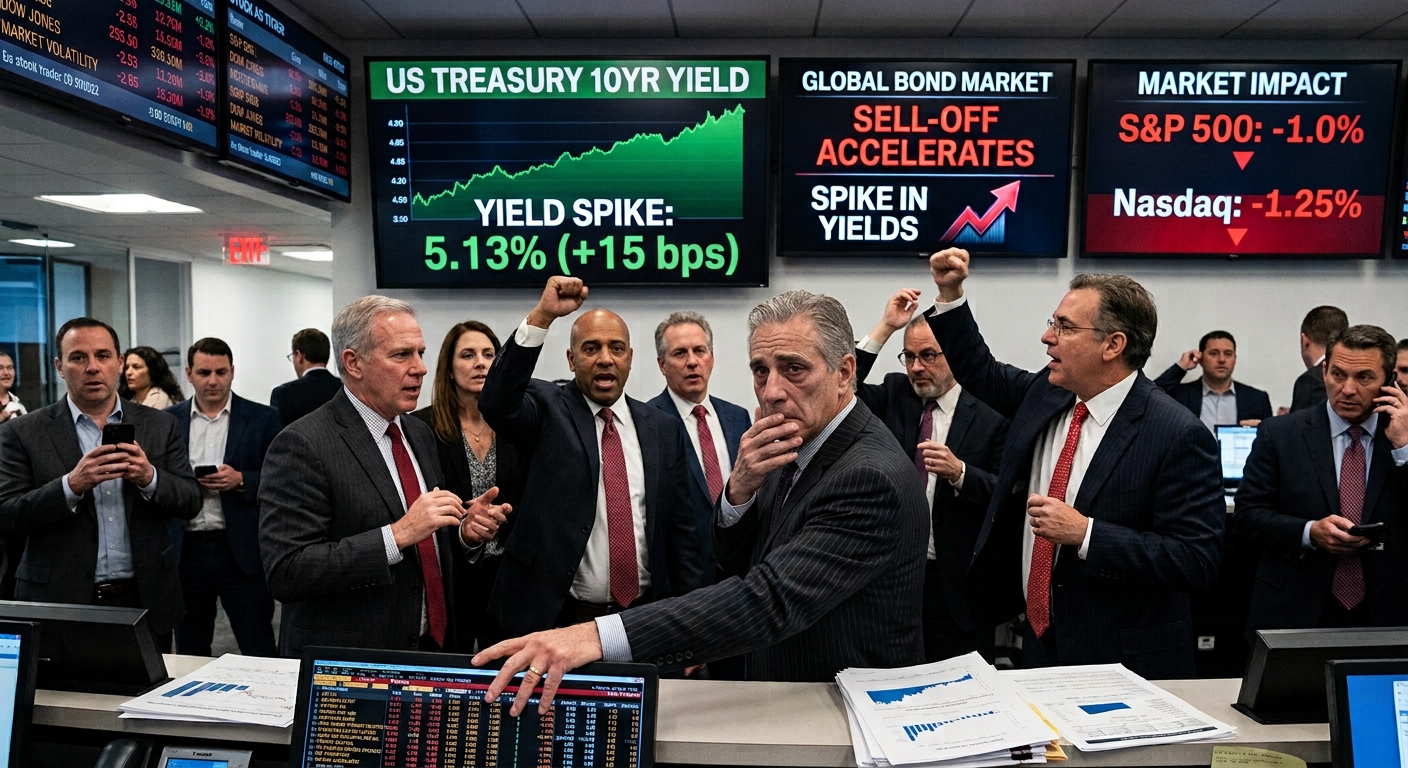
The sharp rises in Treasury yields with the 10-year jumping from 4.92% to 5.24% signals a persistent headwind for equities, despite brief index recoveries driven by dip-buying and easing oil prices.
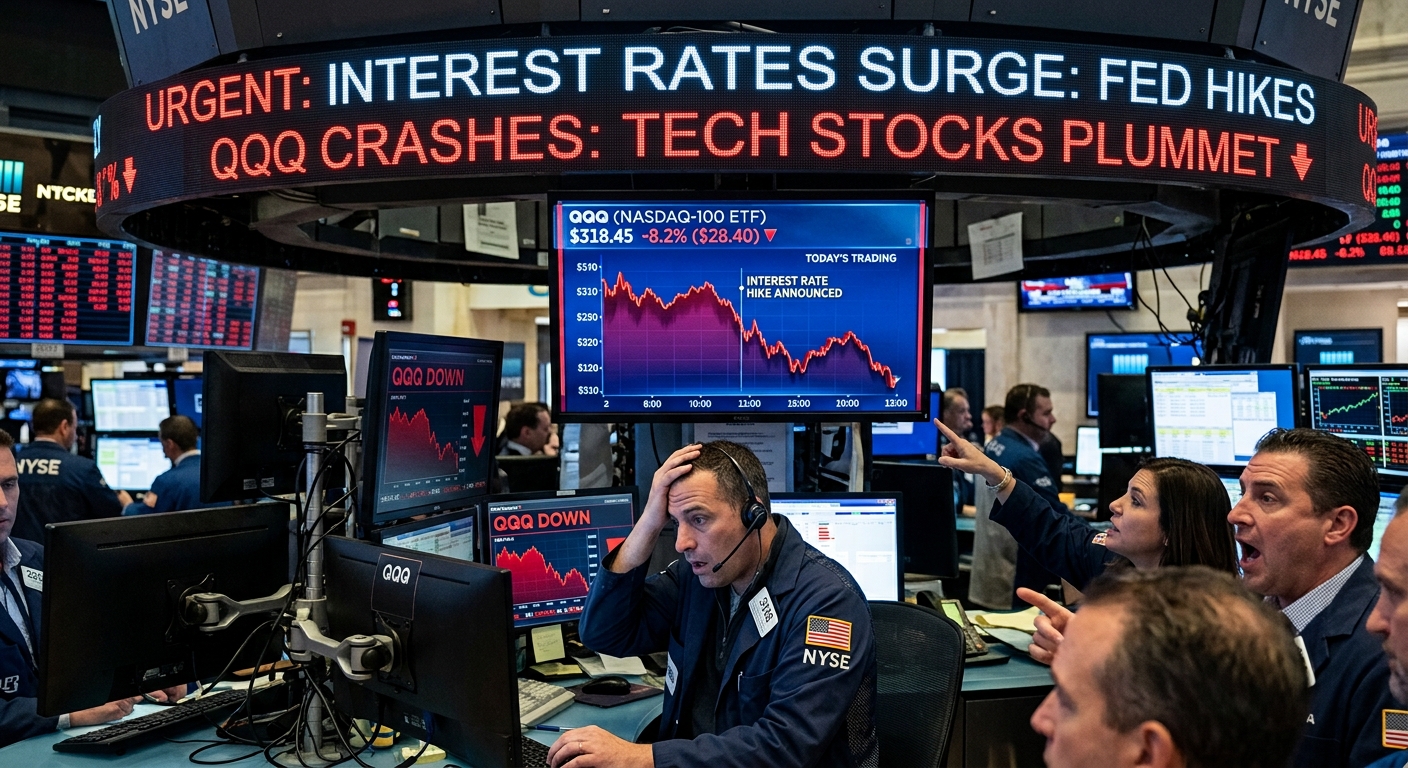
While a strong job market is great for the economy, the demand for credit is leading to a surge in interest rates.
The sharp rises in Treasury yields with the 10-year jumping from 4.92% to 5.24% signals a persistent headwind for equities, despite brief index recoveries driven by dip-buying and easing oil prices.
Both the S&P 500 and Nasdaq Composite reversed near prior highs, with market direction hinging on upcoming macroeconomic data - this looks like the market may have topped out.
Strong labor and manufacturing data may prompt back-to-back Fed rate hikes, sustaining high-interest rates and pressuring equity valuations.
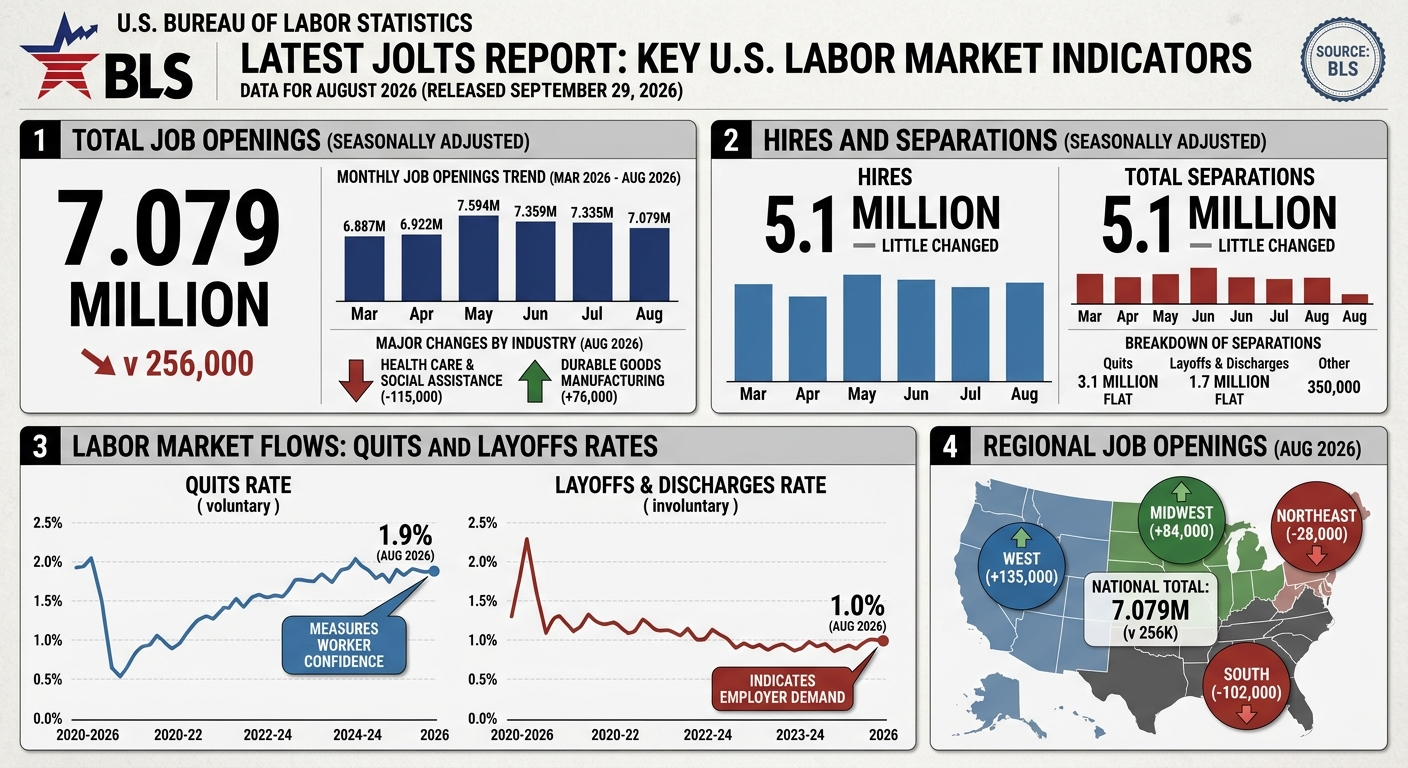
This week’s ADP, ISM, and Non-Farm Payrolls releases are pivotal, with consensus expecting an 84,000 NFP print to reinforce labor market strength.
Read the full article here, on Seeking Alpha, detailing why this week's macro-economic reports could be tough for bonds and stocks.